





The economy is still expanding, but the arithmetic has stopped being generous. Leading indicators are softer at the edges. Current activity remains positive. Lagging measures show strain rather than rupture.
Meanwhile, the operating cost stack is less friendly than the headline inflation number suggests.
This is not a recession call. It is a discipline call.
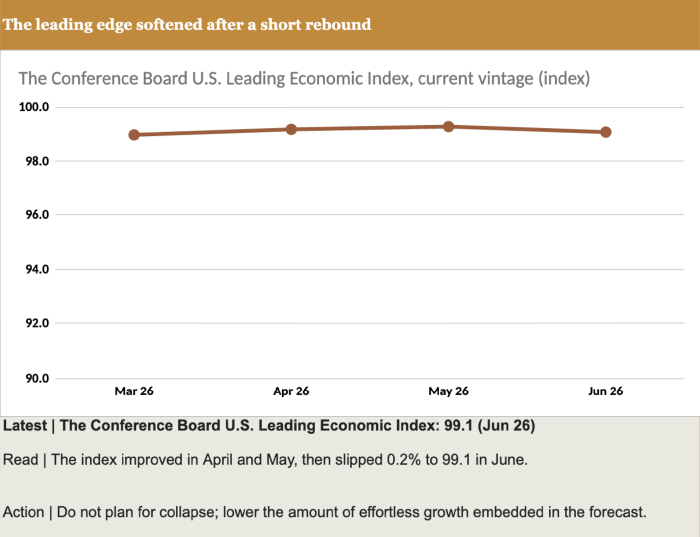
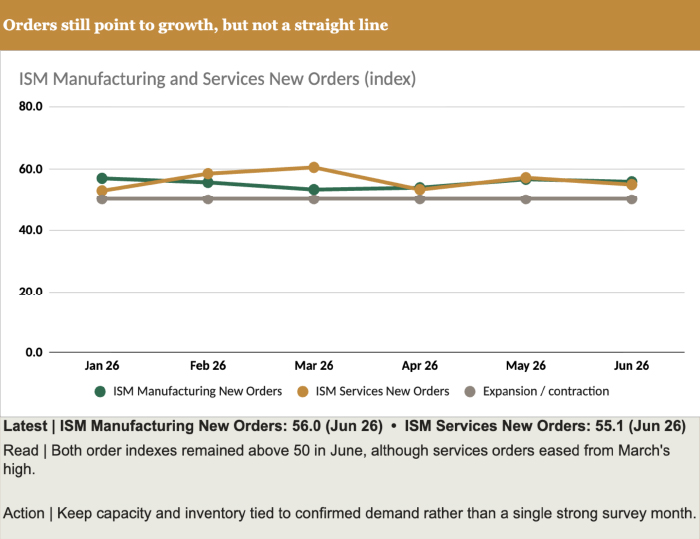
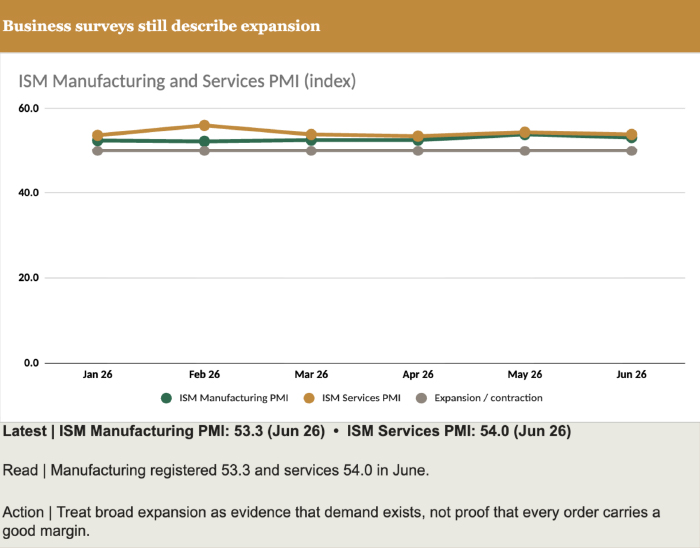
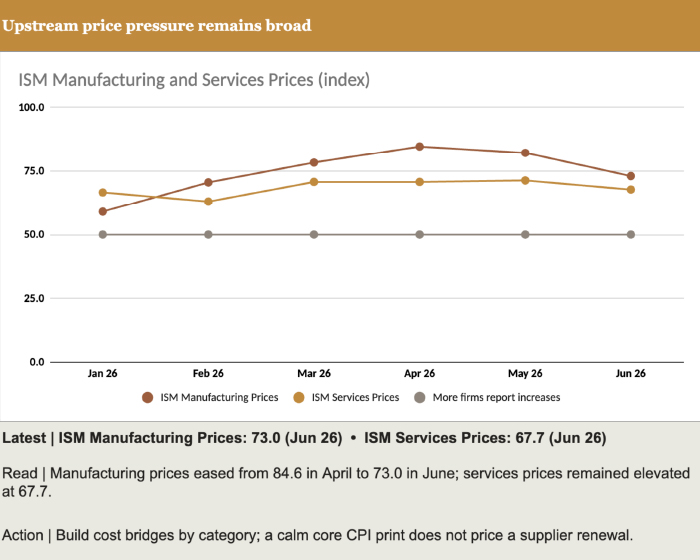
The forward indicators are no longer giving a clean green light. The Conference Board’s Leading Economic Index improved briefly, then slipped 0.2% to 99.1 in June.[1] ISM manufacturing and services new orders remained above 50 at 56.0 and 55.1, which still points to expansion—but not acceleration without interruption.[2][3]
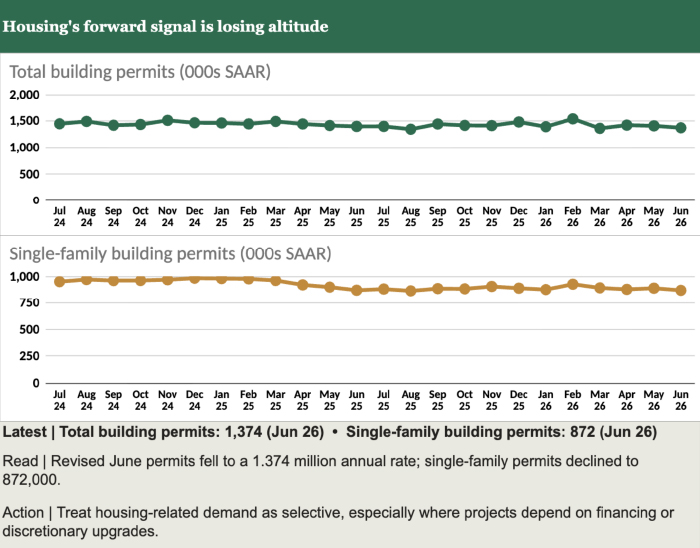
Housing is less encouraging. Revised June building permits fell to a 1.374 million annual rate, while single-family permits declined to 872,000.[4] That matters beyond construction. Housing reaches appliances, furnishings, packaging, transportation, building products and local services.
The labor signal is more reassuring.
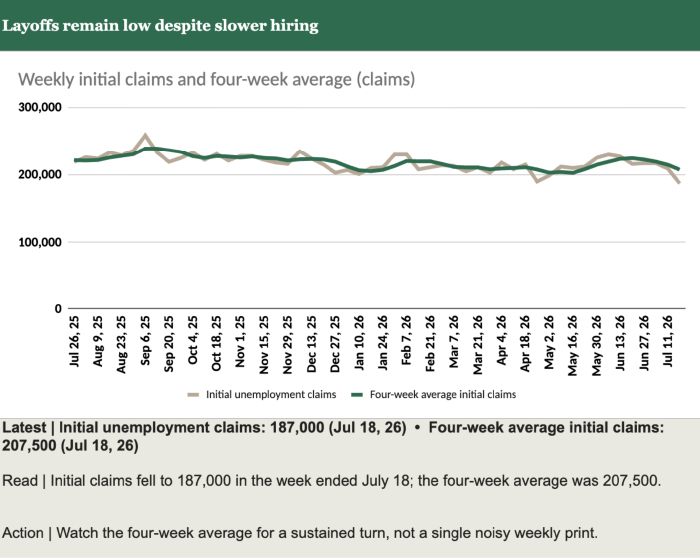
Initial unemployment claims were 187,000 in the week ended July 18, with the four-week average at 207,500.[5] Layoffs remain low even as hiring slows.
The message is not that demand has disappeared. It is that growth should no longer be assumed merely because it showed up last quarter.
Current activity remains positive. The weak spot is conversion.
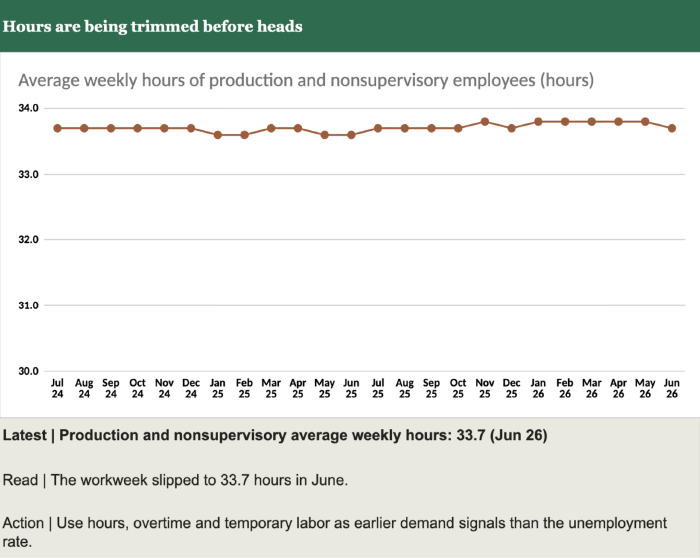
June payrolls increased by only 57,000, while the three-month average fell to roughly 111,000. The production and nonsupervisory workweek slipped to 33.7 hours.[6] Companies are trimming time before broadly trimming people. That is usually how labor cooling begins.
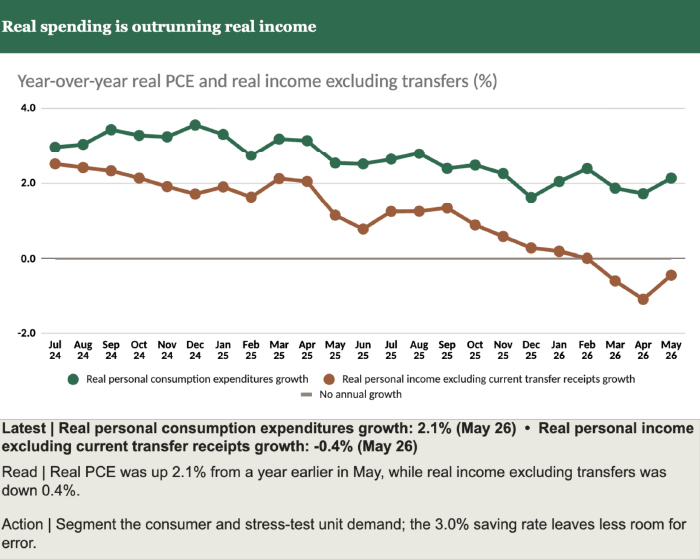
Real consumer spending was still 2.1% higher than a year earlier in May, but real income excluding transfers was down 0.4%. The personal saving rate fell to 3.0%.[8] The consumer is still spending, but the cushion behind that spending is thinner.
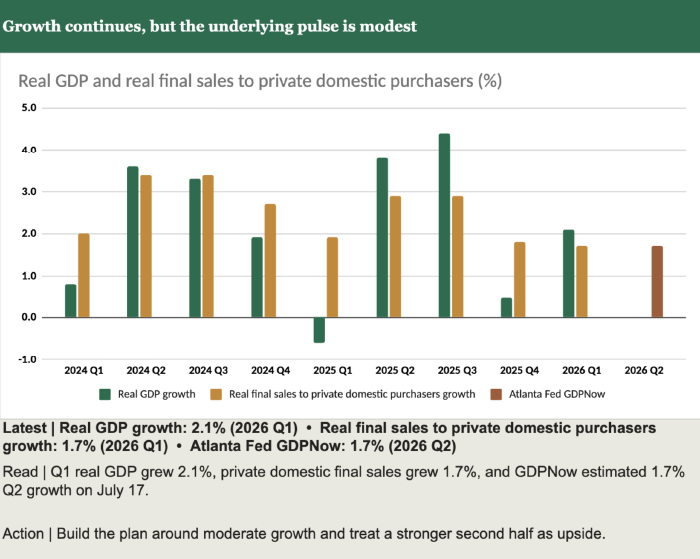
First-quarter real GDP grew at a 2.1% annualized rate, while real final sales to private domestic purchasers—the cleaner measure of underlying private demand—grew 1.7%.[9]
The Atlanta Fed’s GDPNow model estimated second-quarter growth at 1.7% as of July 17.[10] GDPNow is a model estimate, not an official forecast, but it reinforces the same conclusion: growth continues at a moderate pace.
The economy is moving. The margin for operational error is not.
The lagging indicators confirm cooling without confirming rupture.
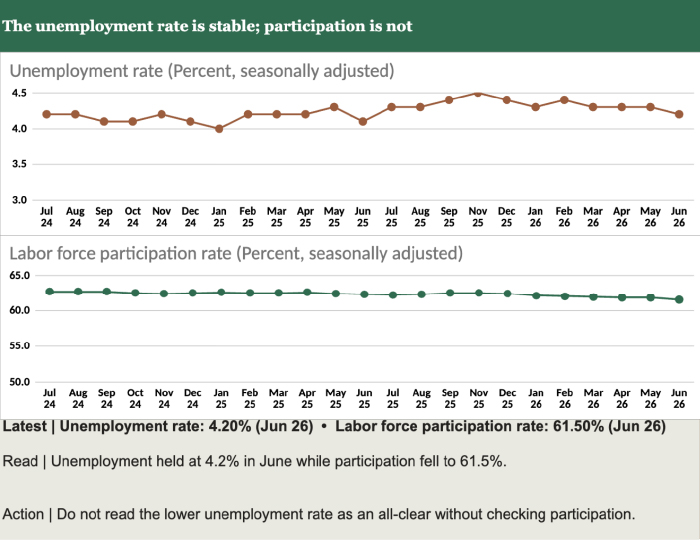
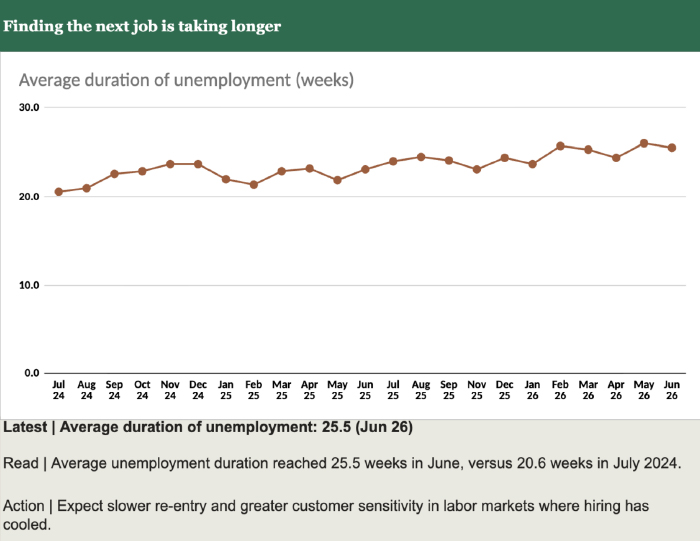
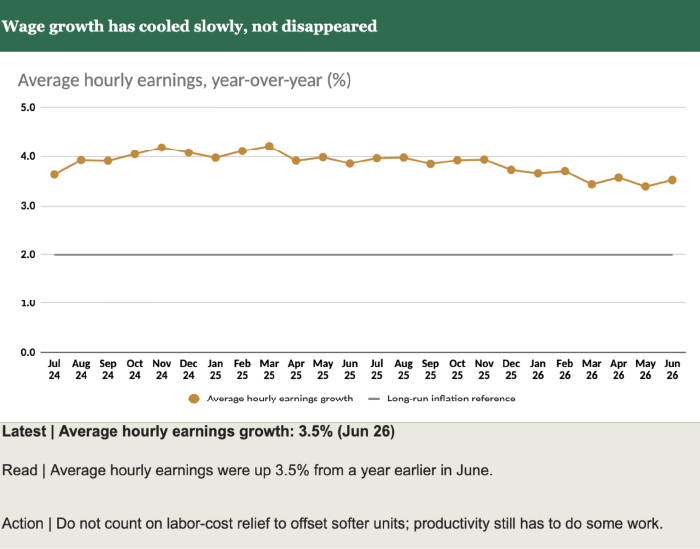
The unemployment rate held at 4.2% in June, but labor-force participation fell to 61.5%. The average unemployed worker had been out of work for 25.5 weeks, and average hourly earnings were still 3.5% higher than a year earlier.[11]
That combination matters.
The unemployment rate looks stable, but job searches are taking longer and fewer people are participating. Labor is cooling slowly, not cleanly.
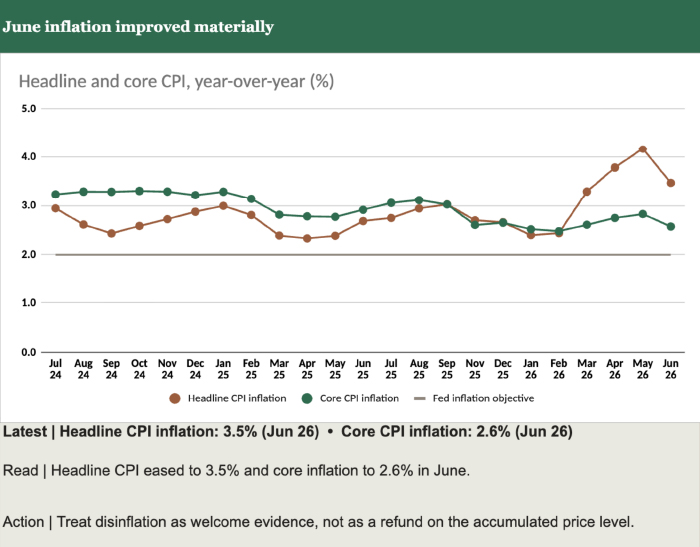
Inflation provided better news. Headline CPI eased to 3.5% year over year in June, while core inflation fell to 2.6%.[12] That is meaningful relief. It is not the same as returning the price level to where it began.
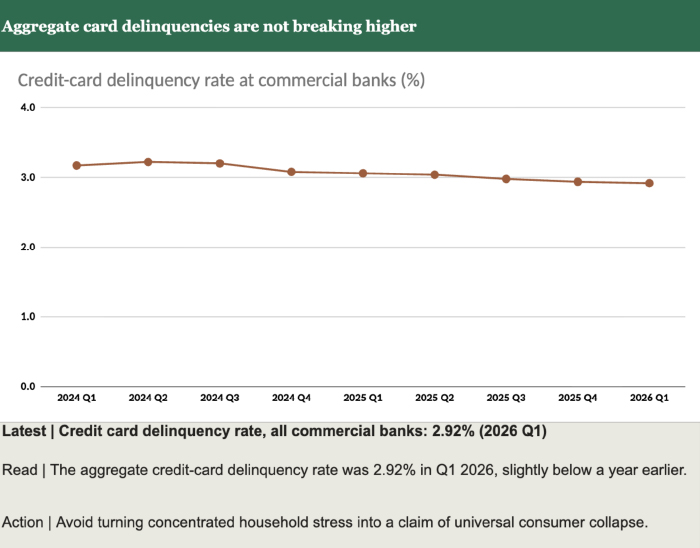
Aggregate credit-card delinquency at commercial banks was 2.92% in the first quarter, slightly below its year-earlier level.[13] Some households are plainly under pressure, but the aggregate data do not support a claim of universal consumer collapse.
The average is stable. The distribution underneath it is not.
June CPI brought real relief. The operating cost stack did not cool in unison.
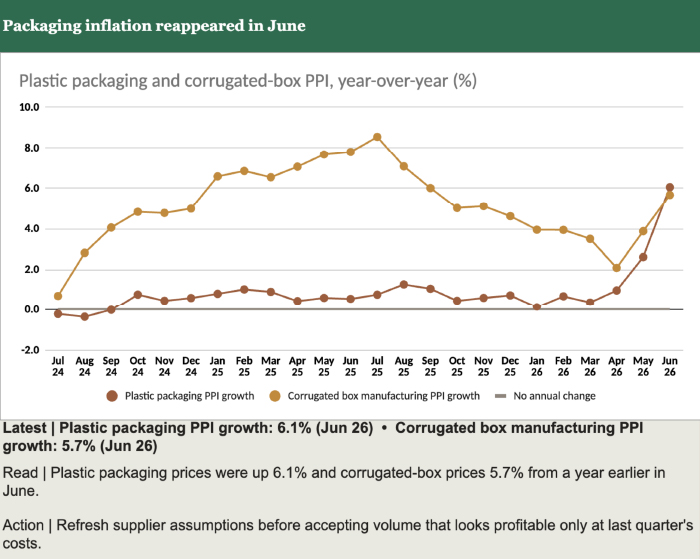
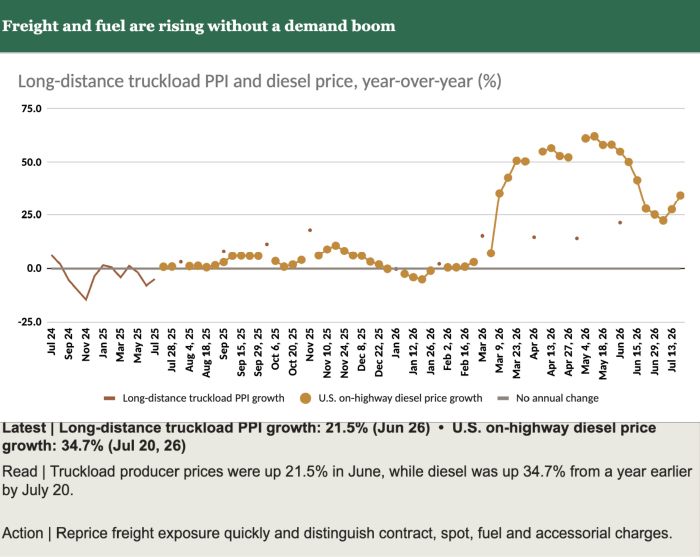
Plastic packaging producer prices were 6.1% higher than a year earlier in June. The industry PPI for corrugated and solid-fiber box manufacturing was up 5.7%.[14] Long-distance truckload producer prices rose 21.5%, while the national diesel price was 34.7% higher than a year earlier by July 20.[15]
These are not interchangeable measures, but they tell the same operator-level story: a business does not pay core CPI.
It pays the supplier invoice, the freight bill, the fuel surcharge, the insurance renewal and the interest expense.
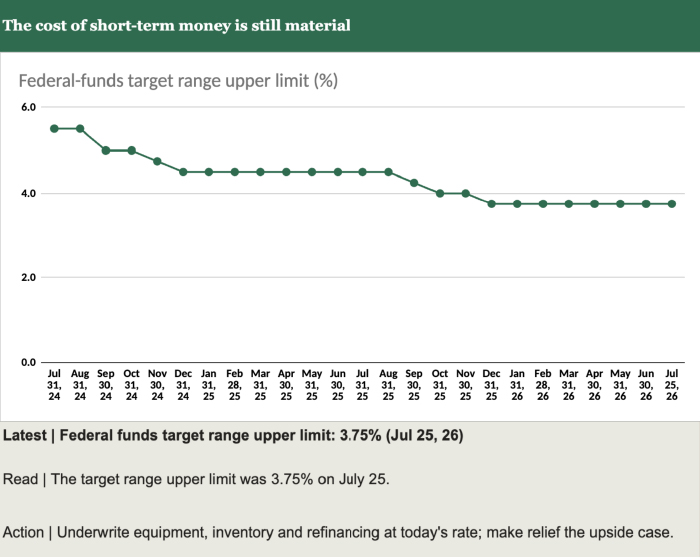
The upper limit of the federal-funds target range remained 3.75%.[16] Banks were selective rather than closed: the April lending survey showed a net 6.6% of banks tightening standards for small firms and 8.1% tightening for large and middle-market borrowers.[17]
Broader markets looked easier. The Chicago Fed National Financial Conditions Index stood at approximately -0.55, indicating looser-than-average market-wide conditions.[18]
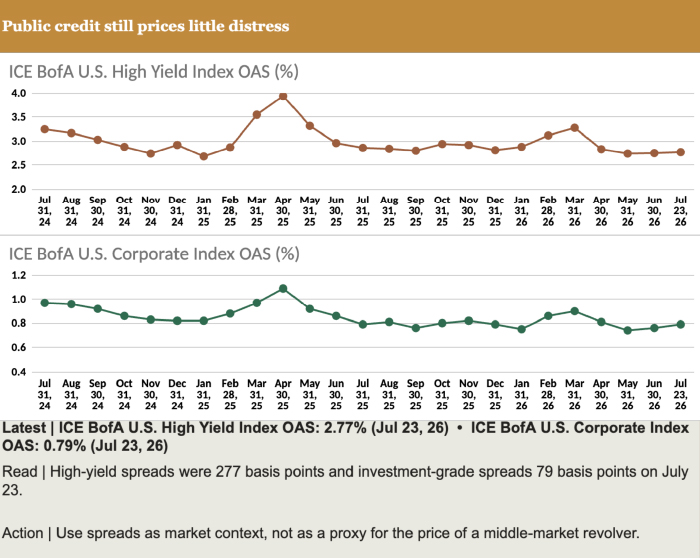
Public credit spreads were also calm, with high-yield spreads near 277 basis points and investment-grade spreads near 79 basis points on July 23.[19]
That difference matters. Easy public markets do not guarantee easy private credit. The lender financing a middle-market revolver still cares about cash conversion, borrowing-base quality, customer concentration, inventory aging and the credibility of EBITDA adjustments.
Do not plan for collapse. Do not plan for effortless growth.
Revenue remains available, but it must be converted into contribution margin and cash. Inventory should follow sell-through, not optimism. Hiring should follow throughput.
Pricing should follow a real cost bridge. Financing plans should work at today’s rate rather than depending on tomorrow’s rate cut.
The strongest operators will not be those with the most confident forecast.
They will be the ones who recognize variance early, explain it clearly and act before the lender or customer forces the issue.
The market prices averages. The business settles in cash.
Revenue is still available. Casual forecasting is getting expensive.
Endnote
[1] The Conference Board, U.S. Leading Economic Index
[2] Institute for Supply Management, June Manufacturing PMI
[3] Institute for Supply Management, June Services PMI
[4] Federal Reserve Economic Data: Total and Single-Family Building Permits
[5] Federal Reserve Economic Data: Initial Unemployment Claims
[6] Federal Reserve Economic Data: Nonfarm Payrolls and Production and Nonsupervisory Workweek
[7] Federal Reserve Economic Data: Industrial Production
[8] Federal Reserve Economic Data: Real Personal Consumption Expenditures, Real Income Excluding Transfers and Personal Saving Rate
[9] Federal Reserve Economic Data: Real GDP and Real Final Sales to Private Domestic Purchasers
[10] Federal Reserve Bank of Atlanta, GDPNow
[11] Federal Reserve Economic Data: Unemployment Rate, Labor-Force Participation, Average Unemployment Duration and Average Hourly Earnings
[12] Federal Reserve Economic Data: Headline CPI and Core CPI
[13] Federal Reserve Economic Data: Credit-Card Delinquency Rate
[14] Federal Reserve Economic Data: Plastic Packaging PPI and Corrugated and Solid-Fiber Box Manufacturing PPI
[15] Federal Reserve Economic Data: Long-Distance Truckload PPI and U.S. On-Highway Diesel Prices
[16] Federal Reserve Economic Data: Federal-Funds Target Range Upper Limit
[17] Federal Reserve Economic Data: Bank Lending Standards for Small Firms and Large and Middle-Market Firms
[18] Federal Reserve Economic Data: National Financial Conditions Index
[19] Federal Reserve Economic Data: ICE BofA U.S. High-Yield OAS and U.S. Corporate OAS
Publication note: Confirm redistribution rights before recreating full histories for the Conference Board LEI, ISM indexes or ICE BofA credit spreads in a public chart.